

X
Seattle
Get In Touch With Us
-

Address:
221 1st Ave W, Suite 200
Seattle, WA, 98119, United States -

Phone: 206-282-3425
-

Fax: 206-282-1199
-

Email: [email protected]
Office Hours:
-
Mon-Fri: 8:00 AM - 4:00 PM
-
Sat: Closed/By Appointment Only
-
Sun: Closed/By Appointment Only
About Seattle
Insurance in Seattle, WA
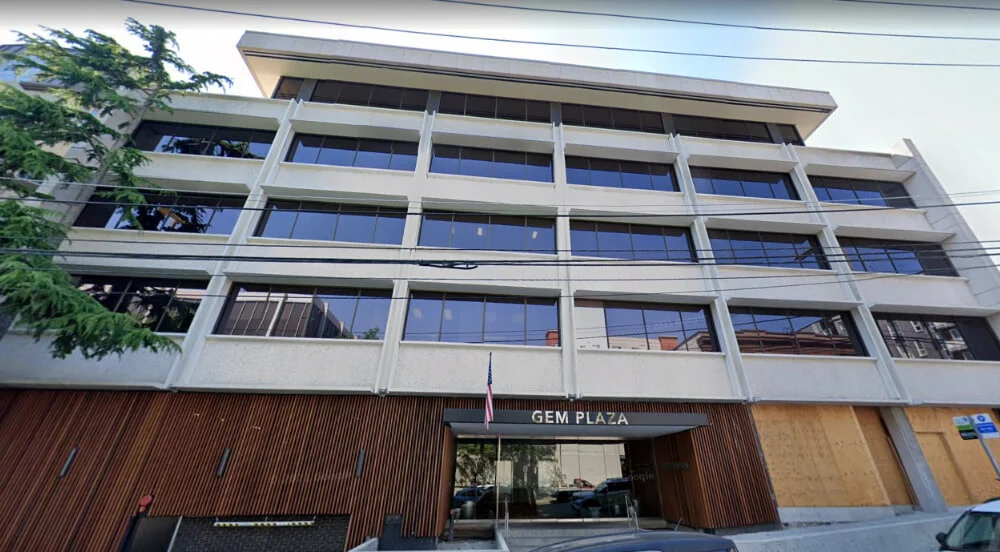
Inszone writes insurance in Seattle, WA from our office at 221 1st Ave W, Suite 200. The office is on 1st Avenue West in Lower Queen Anne, a few blocks north of Seattle Center and a short walk west of the Counterbalance at the foot of Queen Anne Avenue.
This office came to Inszone as Snapp & Son Insurance, and a good part of the book here still knows it by that name. The team stayed, the phone number is the same, and policies carried over.
As an independent insurance agency in Seattle, WA, we represent many carriers rather than one. That matters in Washington, where the two exposures that define the market — Cascadia Subduction Zone earthquake statewide, and wildfire east of the Cascades — sit outside a standard homeowners policy unless somebody adds them deliberately.
Personal Insurance in Seattle, WA
More than half of Seattle households rent, and this office sits in one of the densest apartment neighbourhoods in the city, so renters insurance in Seattle is the policy we write most. It is also the one most often misunderstood: the building owner’s policy pays for the building, not for your belongings and not for a liability claim brought against you. A renters policy is inexpensive relative to what it takes on, and most Seattle leases now require one.
Condo owners have the opposite problem — an HOA master policy that stops somewhere inside the walls, with the gap between it and your unit filled by an HO-6 policy. We read the master policy declarations before quoting, because where that line falls differs building to building.
Drivers shopping car insurance in Seattle should know that Washington’s property damage minimum is $10,000 — low enough to be exceeded by a single newer vehicle in a parking-lot collision. Personal injury protection and uninsured/underinsured motorist coverage must both be offered to you and can only be declined in writing, so the first thing we check on an existing policy is whether a previous agent had them declined.
For owners, home insurance in Seattle turns on two things the premium line does not show: whether earthquake has been added, and how the roof would settle at a claim. Earthquake is excluded from every standard homeowners policy, written separately, and carries a percentage deductible rather than a flat one. Washington take-up is very low relative to the Cascadia hazard and the Seattle Fault, which runs directly under the city through housing stock largely built before current seismic codes. We will price it so you can at least see the number before deciding.
Flood and landslide are excluded as well, and on the slopes above Elliott Bay and Lake Washington both are worth pricing rather than assuming. Boats and watercraft are a steady part of the book here for obvious reasons, alongside landlord policies, personal umbrella liability, motorcycle, RV and collector vehicle coverage.
Life, health, dental and Medicare coverage in Seattle can be quoted through our wider team when a household wants them alongside the property and auto policies.
Business Insurance in Seattle, WA
We insure Seattle businesses across general liability, commercial property, business owner’s policies, commercial auto and fleet, cyber liability, employment practices liability, professional liability and bonds.
Workers’ compensation works differently in this state and it catches out most employers arriving from elsewhere. Washington is a monopolistic state fund state, which means you cannot buy workers’ compensation from a private carrier at all — coverage comes from the Department of Labor and Industries, or through self-insurance if you hold at least $25 million in assets and an approved accident prevention program.
What our insurance brokers in Seattle, WA, place alongside it is the part L&I does not provide: stop-gap employers liability, which answers the employer-liability suits workers’ compensation itself does not, plus USL&H for maritime and dock work and out-of-state coverage for employees working across state lines. On a working waterfront the USL&H question comes up more often than people expect, and the out-of-state gap is the one we find most often on growing payrolls.
Restaurants, retail, contractors, trucking, marine trades, manufacturing, technology firms, healthcare and professional services are all lines we write regularly. Certificates of insurance and additional insured endorsements are turned around quickly, because that is usually what is holding up a lease or a job.
Inszone Insurance agency near me
Our Seattle insurance office is open Monday to Friday, 8:00am to 4:00pm, with weekends by appointment. Call 206-282-3425, use the quote form on this page, or stop by 221 1st Ave W, Suite 200 in Lower Queen Anne.
Working with independent insurance brokers in Seattle means the conversation starts with what you have rather than with one carrier’s product list. From here we also write across Ballard, Magnolia, Fremont, Capitol Hill, West Seattle and the wider King County suburbs. Whether you are insuring a first apartment, comparing a home renewal, pricing earthquake for the first time, or sorting out stop-gap liability for a growing payroll, our insurance specialists can talk through the options available for your situation.
FAQs
Do I need renters insurance in Seattle?
Washington does not require it by law, but most Seattle leases do, and the building owner’s policy pays for the building rather than for your belongings or a liability claim brought against you. A policy usually runs a few dollars a week and includes loss-of-use money if the unit becomes uninhabitable. If your lease names a required liability limit, bring it — the number in the lease decides how the policy is written.
What are the minimum auto insurance requirements in Washington?
Washington requires liability limits of at least $25,000 per person, $50,000 per accident, and $10,000 for property damage. That $10,000 property damage minimum is low enough to be exceeded by a single newer vehicle. Personal injury protection and uninsured/underinsured motorist coverage must both be offered and can only be declined in writing.
Is earthquake covered by my Washington homeowners policy?
No. Earthquake is excluded from the standard homeowners policy and requires a separate policy with a percentage deductible — and Washington take-up is very low relative to the Cascadia hazard and the Seattle Fault, which runs under the city itself. Flood and landslide are excluded as well, which matters on the slopes above Elliott Bay and Lake Washington. On the wildfire side, carriers must give 60 days notice of non-renewal, and the state’s insurance regulator points to defensible space measures like a five-foot noncombustible zone and ten feet of branch clearance as the practical steps that preserve your options.
Does my Seattle business need workers’ compensation insurance?
Yes, from the first worker — but Washington is a monopolistic state fund state, which means you cannot buy workers’ compensation from a private carrier here. Coverage comes from the Department of Labor and Industries, or through self-insurance if you hold at least $25 million in assets and an approved accident prevention program. What we do place alongside it is stop-gap employers liability, which L&I does not provide, plus USL&H and out-of-state coverage for employees working across state lines.
Is this the same office that was Snapp & Son Insurance?
Yes. Snapp & Son Insurance joined Inszone Insurance and the office continues from the same suite on 1st Avenue West in Lower Queen Anne, with the same local team and the same phone number. Policies carried over. If you were a Snapp & Son client and are not sure who handles your account now, call and we will tell you.
How do I get a quote from your Seattle insurance office?
Call 206-282-3425 or use the quote form on this page, and come by 221 1st Ave W, Suite 200 if you would rather do it in person. Have your current declarations page to hand if you can, and for business coverage your annual revenue, payroll by job class and loss runs for the last three to five years. If a carrier has sent you a non-renewal or cancellation notice, bring it — the date on it changes what options are open.
Our Seattle Team
-


How To Get There