

X
Katy
About Katy
Insurance in Katy, TX
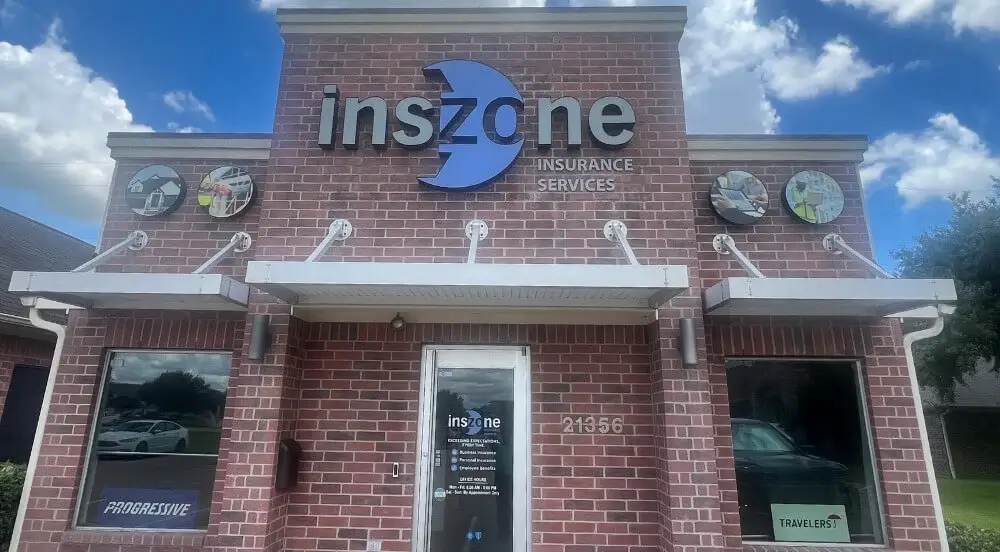
Inszone writes insurance in Katy, TX from our office at 21356 Provincial Blvd. The office is on Provincial Boulevard just off the Katy Freeway, a few miles west of the Barker Reservoir.
This office brings four local agencies under one roof. It was Max Breisse Insurance Agency, and it also took in Caleb Insurance Group, Speck Insurance & Financial Services and Practice Secure Insurance before becoming part of Inszone. If you hold a policy under any of those names, this is the office that services it. Britney Teeters is the Senior Personal Insurance Specialist here.
Anyone looking for an insurance agency in Katy, TX is usually comparing carriers as much as agents. We are independent, so that comparison happens on our side of the desk: we represent many carriers rather than one, and when a carrier tightens its roof rules or pulls back from west Harris and Fort Bend after a storm season, we have somewhere else to go.
Personal Insurance in Katy, TX
For Katy households we write homeowners, auto, renters, condo and landlord policies, personal umbrella liability, flood, and specialty lines including motorcycle, boat, RV and classic car.
Flood is the conversation that matters most in Katy, and it is the one most homeowners here have never had. Flood is excluded from every standard homeowners policy. It is written separately through the National Flood Insurance Program or a private flood carrier, and a new NFIP policy generally carries a 30-day waiting period before it takes effect, so it cannot be bought once a storm is in the forecast. The Addicks and Barker reservoirs sit on Katy’s eastern edge, and much of the Harvey flooding across the Houston area in 2017 happened outside mapped high-risk flood zones, where no lender required flood cover and most people did not carry it.
A good deal of Katy has been built since then, by owners who bought outside a mapped zone and were never asked about flood at closing. Private flood insurance in Texas is an alternative to the NFIP worth comparing, with different limits and waiting periods. A specialist can price both side by side so the decision is made with numbers rather than a flood map.
Hail is the other half of Katy property risk. For homeowners insurance in Katy, TX, expect a separate percentage wind and hail deductible, calculated on the insured value of the house rather than on the claim, and often actual cash value settlement on an older roof. Home insurance in Katy is worth reading for those two lines before anything else, because two quotes at the same premium can settle a hailstorm very differently.
Drivers comparing car insurance in Katy, TX should know Texas requires 30/60/25 liability, and that personal injury protection and uninsured/underinsured motorist coverage must both be included unless you reject them in writing. It is worth checking whether someone rejected them for you — on a busy stretch of I-10 and the Grand Parkway, UM/UIM is the coverage that answers when the other driver carries the minimum or nothing at all.
Renters insurance in Katy, TX is written around your contents and personal liability rather than the building, and — like homeowners — it does not include flood, which is a separate contents-only flood policy for renters.
Katy insurance needs often run wider than a house and two cars. Life, health and Medicare coverage can be quoted through our wider team alongside the property and auto policies.
Business Insurance in Katy, TX
For Katy and west Houston employers, our commercial team places general liability, commercial property, business owner’s policies, commercial auto and fleet, cyber liability, professional liability, surety bonds and commercial flood. The Katy insurance office is a personal-lines team, so business accounts are quoted with Inszone’s commercial specialists — you can still start the conversation here.
Texas is the one state where workers’ compensation is optional for most private employers, and the decision is a real one. An employer who does not subscribe must file an annual notice with the state, post notices and notify each new hire — and gives up the common-law defenses of contributory negligence, fellow servant and assumption of risk, which exposes the business to uncapped compensatory and punitive damages if an injured employee sues. Workers’ compensation remains mandatory for public employers, building and construction contractors on public projects, motor carriers and a few other categories.
Employers who choose not to subscribe often buy occupational accident insurance to provide injury benefits to their people. It is not workers’ compensation and it does not restore the defenses a non-subscriber gives up, so the two decisions have to be made together. We walk through the comparison before you choose either way.
Contractors, energy-sector service firms, retail along the Katy Freeway corridor, restaurants, healthcare and professional services are all lines our commercial team writes. Certificates of insurance and additional insured endorsements are turned around quickly, because that is usually what is holding up a job.
Inszone Insurance agency near me
Our Katy insurance office is open Monday to Friday, 8:00am to 5:00pm. Call 281-578-0523, use the quote form on this page, or come by 21356 Provincial Blvd.
From Provincial Boulevard we also work with clients in Fulshear, Cinco Ranch, Brookshire, Richmond, Cypress and across Waller and west Fort Bend County. Whether you are working out whether your home needs flood cover outside a mapped zone, checking a percentage wind-hail deductible in dollars, adding back UM/UIM somebody once rejected, or deciding between workers’ compensation and non-subscription, our insurance brokers in Katy, TX can talk through the options available for your situation.
FAQs
What are the minimum auto insurance requirements in Texas?
Texas requires liability limits of at least $30,000 per person, $60,000 per accident, and $25,000 for property damage. Texas is not a no-fault state, but personal injury protection and uninsured/underinsured motorist coverage must both be included unless you reject them in writing — so check whether someone rejected them for you.
Do I need flood insurance in Katy if I am not in a flood zone?
Flood is excluded from every standard homeowners and renters policy regardless of your zone, and much of the Harvey flooding across the Houston area happened outside mapped high-risk zones, where lenders do not require flood cover. A new NFIP policy generally carries a 30-day waiting period before it takes effect, with limited exceptions such as a policy tied to a new mortgage, so it has to be in place before a storm rather than bought during one. Private flood carriers are an alternative with their own limits and waiting periods. Whether to carry it is your decision, and a specialist can price both options so you can make it with numbers in front of you.
How do wind and hail work on a Katy homeowners policy?
Expect a separate percentage wind and hail deductible, calculated on the insured value of the house rather than the size of the claim, and often actual cash value settlement on older roofs. Katy is inland, so the coastal Texas Windstorm Insurance Association arrangements that apply along the Gulf do not apply here — wind and hail are written on the homeowners policy itself. Flood is always excluded and written separately.
Does my Katy business need workers’ compensation insurance?
Texas is the one state where workers’ compensation is optional for most private employers. It is mandatory for public employers, building and construction contractors on public projects, motor carriers and a few other categories. If you choose not to subscribe, you must file an annual notice with the state, post notices and notify each new hire — and you give up the common-law defenses of contributory negligence, fellow servant and assumption of risk, which exposes you to unlimited compensatory and punitive damages.
What is occupational accident insurance?
It is a policy that pays defined benefits — medical expenses, disability and death benefits — when a worker is injured on the job, and it is what many Texas employers who do not subscribe to workers’ compensation buy for their employees. It is also common for independent contractors and owner-operator truck drivers. It is not workers’ compensation: it does not carry the same statutory benefits, and for a non-subscribing employer it does not restore the common-law defenses given up by opting out. A specialist can set it next to a workers’ compensation quote so the two can be compared directly.
Is this the same office that was Max Breisse Insurance Agency?
Yes. Max Breisse Insurance Agency, Caleb Insurance Group, Speck Insurance & Financial Services and Practice Secure Insurance all continue from 21356 Provincial Blvd as part of Inszone Insurance, with the same phone number. Policies carried over. If you have paperwork under any of those four names, this is the office that services it.
How do I get a quote from your Katy insurance office?
Call 281-578-0523 or use the quote form on this page, and come by 21356 Provincial Blvd if you would rather do it in person. Have your current declarations page to hand if you can, and for commercial coverage your revenue, payroll by class and recent loss runs. If a carrier has sent you a non-renewal or cancellation notice, bring it — the date on it changes what options are open.
Get In Touch With Us
-

Address:
21356 Provincial Blvd
Katy , TX, 77450, United States -

Phone: 281-578-0523
-

Fax: 866-522-3539
-

Email: [email protected]
Office Hours:
| Mon-Fri: | 8:00 AM – 5:00 PM |
| Sat: | Closed/By Appointment Only |
| Sun: | Closed/By Appointment Only |
Our Katy Team
-


How To Get There