

X
Fort Madison
Get In Touch With Us
-

Address:
711 Avenue G
Fort Madison, IA, 52627, United States -

Phone: 319-372-2055
-

Fax: 319-250-0913
-

Email: [email protected]
Office Hours:
-
Mon-Fri: 8:30 AM – 5:00 PM
-
Sat: Closed/By Appointment Only
-
Sun: Closed/By Appointment Only
About Fort Madison
Insurance in Fort Madison, IA
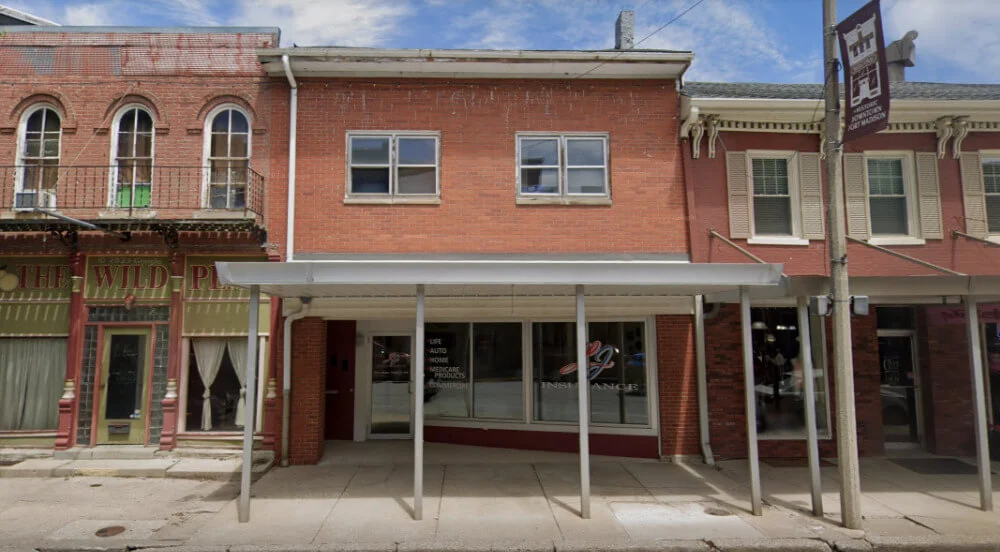
Inszone writes insurance in Fort Madison, IA from our office at 711 Avenue G. The office is on Avenue G in downtown Fort Madison, a short walk from the riverfront and the double-deck swing-span bridge that carries traffic across the Mississippi to Niota, Illinois.
Lee County is the only county in Iowa with two county seats, and Inszone has an office in both — this one in Fort Madison and another on Main Street in Keokuk, 22 miles down the river. Jonna Schneider is the Senior Commercial Lines Account Manager here, and Gariann Sveback is the Personal Lines Account Manager, so both personal and business accounts are handled from this office.
As an independent insurance in Fort Madison, we represent many carriers rather than one. That matters in a river town, where a house near the water, a farm outside town and a shop on Avenue G can each need a carrier with a different appetite, and where a carrier that tightens its roof rules after a storm season does not have to be the end of the conversation.
Personal & Farm Insurance in Fort Madison, IA
For Fort Madison households and farms we write homeowners, auto, renters and landlord policies, personal umbrella liability, farm and acreage coverage, and specialty lines including boats, RVs and motorcycles.
Start with the roof. Many Iowa homeowners policies now carry a roof depreciation schedule — an endorsement that settles a damaged roof by its age and material rather than at full replacement cost. The Iowa Insurance Division has called attention to how widespread these have become. Two quotes at the same premium can pay very different amounts on the same hail claim, so we read the roof terms on every option before we put it in front of you.
The August 2020 derecho, by NOAA’s count the costliest thunderstorm event in U.S. history, still shapes how Iowa carriers write wind and roofs. Since then, wind and hail deductibles set as a percentage of the dwelling limit have become common. On a $200,000 house, a two percent deductible is $4,000 before the policy pays anything.
Flood is written separately. It is excluded from standard Iowa homeowners policies and is placed through the National Flood Insurance Program or a private flood carrier, and an NFIP policy generally has a 30-day waiting period before it takes effect. In Fort Madison, river flood is a question worth asking whichever flood zone the map puts you in.
Drivers comparing auto insurance in Fort Madison, IA should know Iowa sets bodily injury minimums of $20,000 per person and $40,000 per accident, which are among the lowest in the country. Iowa auto insurance must also include uninsured and underinsured motorist coverage unless the named insured rejected it in writing, and a rejection signed years ago can still be on the policy. We check for it.
Acreage is where a standard homeowners policy stops fitting. Homeowners forms generally limit or exclude farming activity, and the liability that comes with livestock, a roadside stand or a neighbour helping at harvest is the part people most often assume is included. Depending on what you run, farm insurance in Fort Madison, IA may mean a full farm policy, a hobby-farm policy or farm liability added to what you already have.
Life insurance and Medicare can be quoted alongside your home and auto policies. For health insurance in Fort Madison, IA, including individual and small-group plans, Inszone’s benefits team can help, and our Keokuk office has a Senior Benefits Insurance Specialist a short drive down the river.
Business Insurance in Fort Madison, IA
For Fort Madison and Lee County employers we place general liability, commercial property, business owner’s and package policies, commercial auto and fleet, cyber and professional liability, employment practices liability, farm operations and surety bonds. Commercial accounts are handled here by our Senior Commercial Lines Account Manager rather than passed to another office.
Iowa workers’ compensation has no employee-count threshold, so coverage is needed effectively from the first hire. Domestic and purely casual employment falls outside it below a $1,500 annual earnings test, and agricultural employers are exempt unless cash payroll to non-exempt workers reached $2,500 in the prior year. Those are narrow exceptions, not a small-business allowance.
Fort Madison’s employers sit on the river and the rail line, and crews often work on both sides of the bridge. If some of your payroll is earned in Illinois, that is worth raising with our commercial team at the quote stage, because the policy has to reflect where the work is done.
Manufacturers, contractors, trucking and transportation firms, farm operations, retail, restaurants and professional offices are all lines we write. Certificates of insurance and additional insured endorsements are turned around quickly, since that is usually what is holding up a job.
Inszone Insurance agency near me
Our Fort Madison insurance office is open Monday to Friday, 8:30am to 5:00pm. Call 319-372-2055, use the quote form on this page, or stop by 711 Avenue G.
From Fort Madison we work with clients across Lee County and into Des Moines County — West Point, Donnellson, Montrose, Burlington and the farms in between. Clients who came to Inszone through LJ Insurance, which served Lee County from Fort Madison and Keokuk, can call either office. Whether you are checking how your roof would settle, pricing river flood, adding acreage to a policy or setting up workers’ compensation for a first hire, our insurance specialists can talk through the options available for your situation.
FAQs
What are the minimum auto insurance requirements in Iowa?
Iowa requires liability limits of at least $20,000 per person, $40,000 per accident, and $15,000 for property damage — among the lowest bodily injury minimums in the country. Uninsured and underinsured motorist coverage must be included unless the named insured rejects it in writing.
What is a roof depreciation schedule?
It is an endorsement on many Iowa homeowners policies that settles a damaged roof by its age and material instead of at full replacement cost. The Iowa Insurance Division has flagged how common these have become. On an older asphalt roof the difference between a scheduled settlement and a replacement-cost settlement can be most of the cost of the new roof, so it is the first line we read on any Iowa policy.
Does homeowners insurance include flood damage from the Mississippi?
No. Flood is excluded from standard homeowners policies in Iowa and is written separately through the National Flood Insurance Program or a private flood carrier. An NFIP policy generally has a 30-day waiting period, so it needs to be in place well before the river rises. A specialist can tell you what flood options are available for your address.
Does my Fort Madison business need workers’ compensation insurance?
Effectively yes, from the first employee — Iowa sets no numeric threshold. Domestic service and purely casual employment are excluded below a $1,500 annual earnings test, and agricultural pursuits are excluded unless cash payroll to non-exempt employees reached $2,500 in the prior year.
I was an LJ Insurance client. Which office has my file?
LJ Insurance served Lee County from Fort Madison and Keokuk and is now part of Inszone Insurance. Call this office on 319-372-2055 or our Keokuk office on Main Street, and either one can find your file. Several unrelated agencies elsewhere in the country also use the LJ name.
How do I get a quote from your Fort Madison insurance office?
Call 319-372-2055 or use the quote form on this page, and come by 711 Avenue G if you would rather do it in person. Have your current declarations page to hand if you can, and for farm or business coverage a list of buildings and equipment, your payroll and recent loss runs. If a carrier has sent you a non-renewal or cancellation notice, bring it — the date on it changes what options are open.
Our Fort Madison Team
-


How To Get There