

X
Placerville
Get In Touch With Us
-

Address:
344 Placerville Dr.
Placerville, CA, 95667, United States -

Phone: 530-621-4433
-

Fax: 916-400-2625
-

Email: [email protected]
Office Hours:
-
Mon-Fri: 9:00 AM – 5:00 PM
-
Sat: Closed/By Appointment Only
-
Sun: Closed/By Appointment Only
About Placerville
Insurance in Placerville, CA
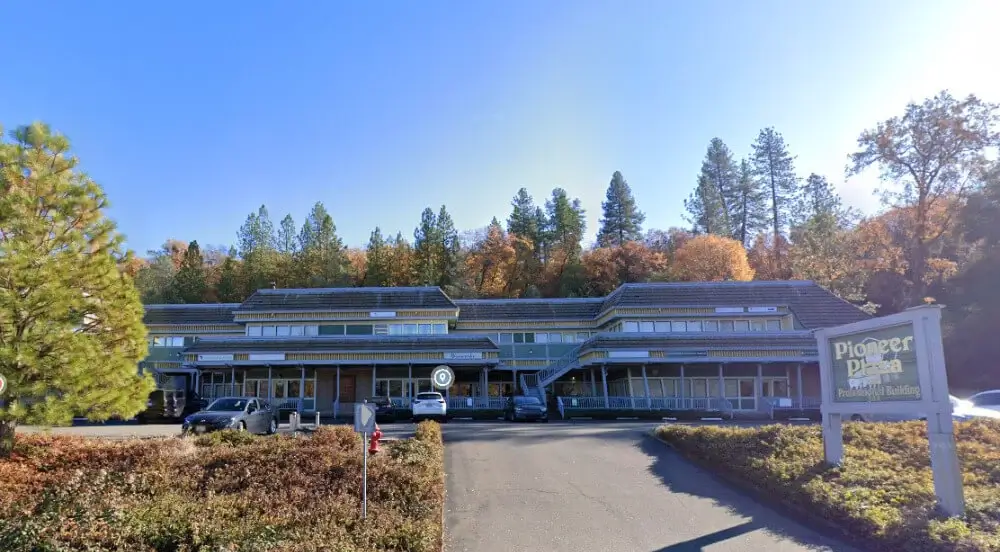
Inszone writes insurance in Placerville, CA from our office at 344 Placerville Dr., Suite 4. The office is on Placerville Drive, just off US-50 and a few minutes west of Main Street and the Bell Tower in Old Hangtown.
This office brings together two El Dorado County agencies. It was Vaught Wright & Bond, a Placerville agency. It also carries the book of Specialty Contractors Insurance Services, which is why contractors make up a large part of the work here. Policies from both carried over.
In the foothills, most insurance conversations start with wildfire. Carriers have paused new business or non-renewed homes across El Dorado County since the 2021 Caldor Fire, and a policy that renewed easily five years ago may not renew at all now. As an independent agency we represent many carriers rather than one, so when a carrier pulls back from a ZIP code or a ridge line, we have somewhere else to go.
Personal Insurance in Placerville, CA
For Placerville households we write homeowners, dwelling fire, condo, renters and landlord policies, auto, personal umbrella liability, earthquake coverage, and specialty lines including motorcycles, RVs, boats and classic cars.
Many people here ask for fire insurance in Placerville, CA, and it means something specific. A dwelling fire policy is written for fire and a short list of other perils, without the theft, water damage and liability a full homeowners policy includes. It is often what is available on a home in a high fire hazard area, and it is usually paired with a difference in conditions policy that adds back what the fire policy leaves out.
If your homeowners insurance in Placerville, CA is non-renewed, California requires at least 75 days’ notice, and that window is the time to act. We start with the admitted carriers still writing in El Dorado County, move to surplus lines if they decline, and only then look at a residual-market fire policy with a difference in conditions wrap. The price question comes last, because in this market the first question is who will write the home at all.
Mitigation now counts. Under California’s Safer from Wildfires rules, insurers must recognize specific steps in their rates, including a Class A fire-rated roof, ember-resistant vents, a cleared five-foot zone around the house and defensible space. State law requires up to 100 feet of defensible space around structures in fire hazard areas, and a documented inspection can help when a carrier is deciding whether to renew. We ask which steps you have taken and look for carriers that give credit for them.
Cabins toward Pollock Pines and the Sierra are judged on the same wildfire factors plus access in winter and whether anyone lives there year-round. Earthquake is excluded from standard homeowners policies and can be written separately, often through the California Earthquake Authority.
Drivers comparing car insurance in Placerville, CA should know California raised its liability minimums on January 1, 2025, to $30,000 per person, $60,000 per accident and $15,000 for property damage. On US-50 between Sacramento and Tahoe, many households price higher limits alongside the minimum. Renters, life and health coverage can be quoted alongside your home and auto.
Business Insurance in Placerville, CA
For Placerville and El Dorado County businesses we place general liability, commercial property, business owner’s policies, commercial auto, workers’ compensation, professional liability and surety bonds, working with Inszone’s commercial team where an account needs it.
Contractors are a large part of this office’s book. Every California contractor needs a contractor license bond on file with the CSLB, currently $25,000, and LLC contractors must also carry general liability insurance and an additional LLC worker bond. Contractor insurance in California usually starts with general liability sized to the jobs you bid, then workers’ compensation, commercial auto and tools and equipment. We keep the bond, the certificates and the renewal dates in one place so a lapse does not hold up a licence or a job.
California requires workers’ compensation from the first employee, with no small-employer exemption, and five contractor classifications must carry it even with no employees at all. Restaurants and shops on Main Street, tourism and hospitality businesses, and professional offices are all lines we write. Certificates of insurance and additional insured endorsements are turned around quickly, because that is usually what is holding up a job.
Inszone Insurance agency near me
Our Placerville insurance office is open Monday to Friday, 9:00am to 5:00pm, with weekends by appointment. Call 530-621-4433, use the quote form on this page, or come by 344 Placerville Dr., Suite 4.
From Placerville we work with clients across El Dorado County, including Diamond Springs, El Dorado Hills, Cameron Park, Shingle Springs, Camino and Pollock Pines. Whether you have just received a non-renewal notice, are pricing a fire policy and a wrap, documenting defensible space, or renewing a contractor license bond, our insurance specialists can talk through the options available for your situation.
FAQs
What are the minimum auto insurance requirements in California?
California requires liability limits of at least $30,000 per person, $60,000 per accident, and $15,000 for property damage. Those limits took effect January 1, 2025 — the first increase since 1967 — and they rise again to $50,000 / $100,000 / $25,000 on January 1, 2035. The minimum keeps you legal, but anything above your limit comes out of your own assets, which is why we usually price higher limits alongside it.
My home insurance wasn’t renewed. What are my options?
More than most people expect, and they run in order. California requires at least 75 days’ notice of a homeowners non-renewal, so start as soon as the notice arrives. We re-shop the admitted carriers still writing in your area first. If they decline, we go to surplus lines carriers. If that fails, a residual-market fire policy can be paired with a difference in conditions policy to add back the liability, theft and water damage coverage the fire policy leaves out. Bring the notice and your current declarations page.
What is the difference between fire insurance and homeowners insurance?
A dwelling fire policy is written for fire and a limited list of other perils, while a homeowners policy adds theft, water damage, personal liability and more. In high fire hazard areas a fire policy is often what is available, and a difference in conditions policy can be added to fill most of the gap. A specialist can lay the two side by side for your home.
Does my Placerville business need workers’ compensation insurance?
Yes. Under California Labor Code section 3700, every employer with one or more employees must carry workers’ compensation — there is no small-employer exemption. Five contractor classifications must carry it even with no employees at all: C-8 Concrete, C-20 Warm-Air Heating/HVAC, C-22 Asbestos Abatement, C-39 Roofing, and C-61/D-49 Tree Service. Every other licensee can still file a no-employee exemption until January 1, 2028.
Is this the same office as Vaught Wright & Bond and Specialty Contractors Insurance Services?
Yes. Both agencies are now part of Inszone Insurance, and this office at 344 Placerville Dr., Suite 4 carries their clients. Policies carried over, and the phone number is 530-621-4433.
How do I get a quote from your Placerville insurance office?
Call 530-621-4433 or use the quote form on this page, and come by 344 Placerville Dr., Suite 4 if you would rather do it in person. Have your current declarations page to hand if you can, any non-renewal notice, and a list of the wildfire mitigation you have done. For contractor coverage, bring your licence number, payroll by class and recent loss runs.