

X
Denver
Get In Touch With Us
-

Address:
2530 N. Washington St. Ste. 100
Denver, CO, 80205, United States -

Phone: 800-409-9790
-

Fax: 888-645-4229
-

Email: [email protected]
Office Hours:
-
Mon-Fri: 8:00 AM - 5:00 PM
-
Sat: Closed/By Appointment Only
-
Sun: Closed/By Appointment Only
About Denver
Insurance in Denver, CO
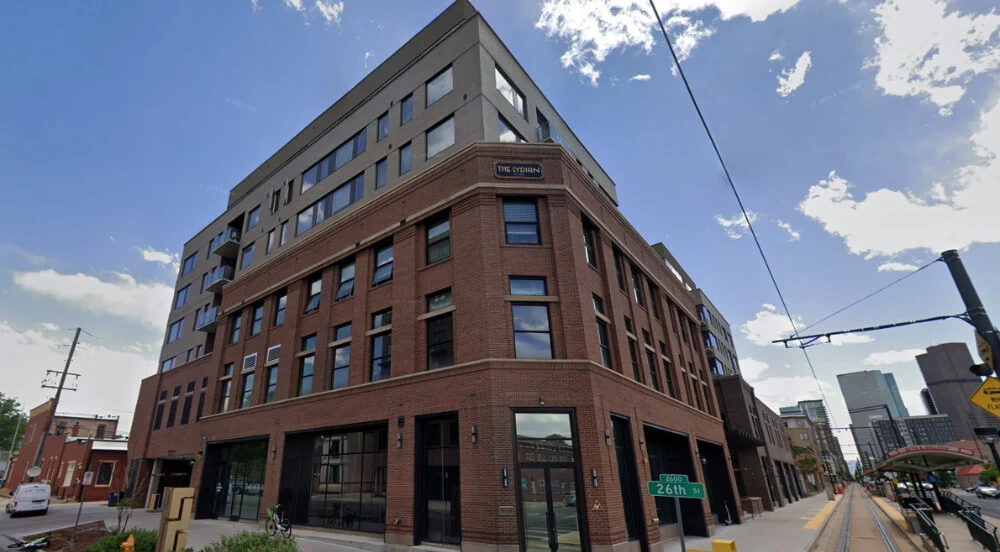
Inszone writes insurance in Denver, CO from our office at 2530 N. Washington St. Ste. 100. The office is on North Washington Street just above Five Points, a few minutes from the RiNo warehouses and the I-70 interchange.
This office came to Inszone as Loft & Co, and part of the book here still knows it by that name. The team stayed and the accounts carried over.
Working with independent insurance brokers in Denver, CO means the conversation starts with the risk in front of you rather than with one carrier’s product list. That matters in a market where hail has reshaped what carriers will write: roof schedules, percentage wind-hail deductibles and cosmetic damage exclusions now vary enough between carriers that two quotes at the same premium can be very different policies.
Personal Insurance in Denver, CO
For Denver households we write homeowners, renters and condo policies, landlord coverage for rental property, personal umbrella liability, and specialty lines including motorcycle, RV and collector vehicles.
Hail is the loss that sets Colorado premiums, and it is where the fine print has moved fastest. Most homeowners policies here now carry a separate or percentage wind-hail deductible rather than a flat one, a roof settlement schedule that reduces payment as the roof ages, and sometimes a cosmetic damage exclusion that treats dented metal as an appearance issue rather than damage. Those three clauses decide what a hail claim actually pays, and none of them appear on the premium line.
Where a home cannot find coverage in the admitted market at all, Colorado now operates a state-backed residual market for basic property coverage, opened to residential applicants in 2025. It is a last resort rather than a substitute, and it is usually paired with a difference-in-conditions policy to fill what it leaves out. We will tell you plainly if that is the conversation you are in.
Drivers comparing car insurance in Denver should know that $5,000 of medical payments coverage and uninsured/underinsured motorist coverage are both included on a Colorado policy by default unless rejected in writing. A previous agent may have rejected them years ago, so it is the first thing we look at on an existing policy.
Denver is a renter-heavy city, and renters insurance in Denver is the policy most often misunderstood. The building owner’s policy pays for the building, not for your belongings and not for a liability claim brought against you, and most leases in this market now require a policy with a stated liability limit.
Life, health and Medicare coverage can be quoted through our wider team when a household wants them alongside the property and auto policies.
Business Insurance in Denver, CO
Commercial lines are what this office does. The team here is built for it: three commercial specialists, including two senior account roles and a QCLS designation, working Denver-metro accounts day to day.
We place business insurance in Denver across general liability, commercial property, business owner’s and commercial package policies, commercial auto and fleet, cyber liability, employment practices liability, professional liability, and surety bonds.
Workers’ compensation is not optional in Colorado and the threshold is one. Coverage is required from the first employee, including part-time workers and family members — anyone paid for their services is presumed to be an employee — and the penalty for going without runs to $500 a day. Certain corporate officers and LLC members holding at least 10% ownership can reject coverage for themselves, which is the exemption most small crews and owner-operators end up asking about.
Contractors, construction and trades, restaurants and hospitality, professional services, transportation, real estate and habitational accounts are all lines we write regularly. Certificates of insurance and additional insured endorsements are turned around quickly, because that is usually what is holding up a contract.
Inszone Insurance agency near me
Our Denver insurance office is open Monday to Friday, 8:00am to 5:00pm, with weekends by appointment. Call 800-409-9790, use the quote form on this page, or stop by 2530 N. Washington St. Ste. 100.
From here we work across the Denver metro — Five Points, RiNo and downtown, out to Aurora, Lakewood, Thornton and Commerce City, and down the south corridor. Whether you are checking how your roof would settle after a hail season, insuring a first apartment, adding a vehicle to a fleet, or sorting out workers’ compensation for a new hire, our insurance agents in Denver, CO, can talk through the options available for your situation.
FAQs
What are the minimum auto insurance requirements in Colorado?
Colorado requires liability limits of at least $25,000 per person, $50,000 per accident, and $15,000 for property damage. Two things get missed here: $5,000 of medical payments coverage and uninsured/underinsured motorist coverage are both included by default unless you reject them in writing.
Why is my wind and hail deductible different from the rest of my policy?
Because most Colorado homeowners policies now carry a separate or percentage wind-hail deductible, plus roof settlement schedules that reduce payment as the roof ages, and sometimes a cosmetic damage exclusion. A percentage deductible is calculated on the dwelling limit rather than the claim, so on a higher-valued home it can be a large number. Colorado also opened a state-backed residual market to residential applicants in 2025 for owners who cannot find coverage in the admitted market. We walk through all of it before you sign.
Does my Denver business need workers’ compensation insurance?
Yes. Colorado requires coverage from the first employee, including part-time workers and family members — anyone paid for their services is presumed to be an employee. Penalties run up to $500 a day. Certain corporate officers and LLC members with at least 10% ownership can reject coverage for themselves.
Is this office set up for business insurance or personal insurance?
Both, with commercial as the day-to-day focus. The three specialists based here are all commercial lines, so business accounts are handled in this office start to finish. Home, auto and renters policies are written here too, with the wider Inszone team behind them for life, health and Medicare. If you are not sure who should handle your account, call and we will route it.
Is this the same office that was Loft & Co?
Yes. Loft & Co joined Inszone Insurance and this office continues from 2530 N. Washington St. with the same team. Accounts carried over. Inszone also has a Greenwood Village office at 5990 Greenwood Plaza Blvd that came from the same group, so if you were a Loft client and are not sure which office holds your file, either can look it up.
How do I get a quote from your Denver insurance office?
Call 800-409-9790 or use the quote form on this page, and come by 2530 N. Washington St. Ste. 100 if you would rather do it in person. Have your current declarations page to hand if you can, and for business coverage your annual revenue, payroll by class code and loss runs for the last three to five years. If a carrier has sent you a non-renewal or cancellation notice, bring it — the date on it changes what options are open.
Our Denver Team
-


How To Get There