An artisan contractor is a skilled tradesperson, such as a plumber, electrician, painter, or landscaper, hired to perform specialized, hands-on work rather than oversee an entire project. Because artisan contractors work on other people’s property with tools and materials, the right mix of liability, tools, and auto coverage is essential. For artisan contractors like plumbers, electricians, landscapers, or roofers, it’s crucial to procure the right insurance type and coverage. Various complexities involved in the duties and tasks of artisan contractors can lead to unfortunate incidents, such as injuries or property damage.
Key Points
- An artisan contractor is a skilled tradesperson — plumbers, electricians, painters, roofers, and similar trades — hired for specialized work rather than full project oversight.
- General liability insurance protects artisan contractors against third-party claims for property damage or bodily injury on the job.
- “Artisan use” on a personal auto policy covers occasional use of a vehicle to carry tools and materials to job sites; heavier use usually requires a full commercial auto policy.
- California requires a CSLB license for any contracting job worth $1,000 or more in combined labor and materials, effective January 2025 (up from $500).
- Nationally there are over 340,000 construction/maintenance painters, with 4% projected job growth through 2034 (BLS).
Who is considered an artisan contractor?
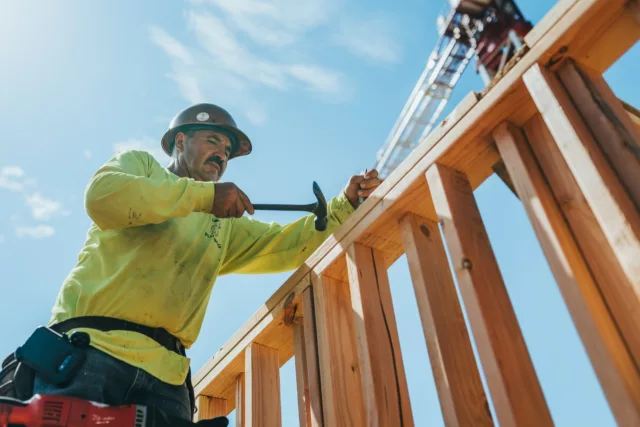
Artisan contractors, also known as special trade contractors, are individuals or organizations that are hired to handle specialized projects requiring a highly developed and specific skill set. Electricians, framers, roofers, masons and plumbers are some examples of artisan contractors. They are hired often as subcontractors to handle certain stages of a larger project so that general contractors can deliver a project in its entirety. Regardless of your specialization, securing appropriate insurance policies is the optimal way to safeguard your business, yourself, and your employees.
Are you an artisan contractor! Learn from the experts and get your free quote today!
Types of Insurance to Consider
Aside from tools of the trade, acquiring an insurance policy is one of the smartest investments for an artisan contractor to make. With all of the moving parts to a job site accident are a matter of when not if. These policies have a variety of different nuances and options to choose from. Here are some of the policies we highly recommend you purchase:
Commercial General Liability Insurance
Common General Liability Coverages can include:
- Property Damage: In the case that third party property is damaged by yourself or by an employee, General Liability can cover the cost of the damage and loss of use of the property.
- Damage to Rented or Leased Premises: Covers any damage to property an artisan contractor rents or leases.
- Medical Payments: this coverage pays any medical expenses regardless of who is at fault. Lawsuits can be prevented if medical payments are refunded.
- Bodily Injury: In the case that you or one of your employees causes injury to a third party, medical expenses, compensation loss and other costs that are related to the loss of services are covered.
- Personal Injury: In case there is harm to somebody’s reputation or livelihood.
- Legal expenses: Fees related to the aforementioned circumstances.

Business Auto Insurance
Automotive accidents happen, statistically more often than any other type of insurance claim. A study showed that when large vehicles, including trucks, are involved in accidents, the cost of the damage came to an average of approximately $60,000 and resulted in 4,102 deaths a year (2019).
Having business auto insurance, you are covered against third-party claims such as injuries, vehicle damage or loss to property. Similar with commercial general liability insurance, the legal expenses will also be covered whenever things get to court.
Take note that a personal auto policy will not provide coverage for any vehicle owned by the contracting business. These vehicles must have a business auto policy.
Inland Marine Insurance
Inland Marine insurance covers goods that are in transit over land, certain types of moveable property and the transportation of equipment. Inland marine insurance, though known as “floater” policies, is essential especially when the materials, supplies and tools are being transported to and from the construction site. Regardless of who is driving from point A to B, inland marine coverage ensures safe arrival and will compensate for any accidents.
Workers Compensation
Artisan contractors are also responsible for the safety of their employees.
Workers’ compensation covers a contractor’s employee if ever they get injured, contract diseases or even lose their lives during the construction project. Coverages usually include medical treatment, rehabilitation costs, disability income and compensation for the loved ones of the workers injured on the job. This insurance policy even provides protection to employers against claims filed in court by the families of a badly injured or deceased employee.
Contractor’s Pollution Insurance
This insurance policy provides contractors coverage for bodily injury, defense, property damage and cleanup costs in the case of pollution arising from an artisan contractor’s work on a project.
This insurance policy is often unique to the specific type of contractor, mainly because of the wide variation of environmental risks and types of contractors, in addition to the various types of projects a contractor works on. Policies are offered either on the basis of occurrence or claims and can be on a blanket program or on certain projects.
Business Owner’s Policy (BOP)
If you’re looking into a more affordable and bundled insurance policy for your business, business owner’s policy (BOP) can be a good choice. This policy combines protection for all the major property and liability risks into one package. It includes the important coverages required in the business and often costs less than the total costs of the individual insurance policies.
 Artisan and Service Contractor Policies
Many insurance carriers now combine general liability coverage for artisan trades (hands-on work like plumbing, electrical, or painting) and service contractors (non-construction service work like landscaping or cleaning) into a single “artisan and service contractor” program. For a small trade business, this bundled approach is often simpler and more cost-effective to bind than assembling separate policies for each type of work.
Protecting Your Tools and Equipment From Theft
Tool theft is one of the most common losses artisan contractors file claims for. A few practical steps reduce the risk: lock toolboxes and trailers with hardened padlocks, park work vehicles in secured or well-lit areas overnight, engrave or photograph high-value tools for identification, and keep an updated inventory with serial numbers on file. Inland marine insurance (see below) is the coverage that responds when tools are stolen or damaged in transit or at a job site.
California Contractor Insurance Guide
California requires a CSLB license for most contracting work. As of January 2025, the minor-work exemption threshold rose from $500 to $1,000 in combined labor and materials — but only applies if the job needs no permit and you hire no help. A painting and decorating contractor, for example, needs the C-33 specialty license, which — like nearly every CSLB classification — requires maintaining a $25,000 contractor’s license bond. The CSLB doesn’t set a statewide minimum for general liability insurance, but most general contractors and property owners require proof of coverage before letting a subcontractor on a job site.
What’s Changed for Artisan Contractors in 2026
Demand for skilled trades remains strong
There are more than 340,000 construction and maintenance painters working nationally, with 4% projected job growth through 2034 — similar patterns hold across most artisan trades (BLS).
California’s licensing threshold has changed.
As of January 2025, unlicensed work is allowed up to $1,000 in combined labor and materials (up from $500) — but only if the job needs no permit and involves no hired help. Most real contracting jobs still require a CSLB license (AB 2622).
Combined artisan and service-contractor programs are more common.
Many carriers now bundle general liability for trade work alongside service-based work like landscaping or cleaning into a single streamlined policy, rather than requiring separate programs
Additional coverage needs vary by trade
Depending on your specialty, you may need professional liability for design-related work, commercial auto for business-titled vehicles, or cyber liability if you handle customer payment data.
Conclusion
Risks are always present in every business, contractors are not the exception. For every potential risk, there is an insurance policy that can cover you, your employees and your property.
You can’t buy coverage after the fact, so you need to have a policy in place before these work-related risks appear. Plan and protect your contracting business for the unexpected, the earlier the better.
Frequently Asked Questions About Artisan Contractor Insurance
What is an artisan contractor in insurance terms?
In insurance terms, an artisan contractor (sometimes called a special trade or artisan and service contractor) is a skilled tradesperson — a plumber, electrician, painter, roofer, or landscaper, for example — who performs specialized, hands-on work rather than managing an entire construction project. Insurers rate artisan contractors separately from general contractors because of their narrower, trade-specific risk exposures.
What is the difference between artisan contractor and general contractor coverage?
General contractor coverage has to account for overseeing an entire project and multiple subcontractors, often at broader scope and higher limits. Artisan contractor coverage is scoped to a single trade’s specific exposures — a painter’s policy, for example, focuses on paint and ladder-related property damage rather than framing or excavation risk.
Do painters need a contractor’s bond?
In California, painting and decorating contractors (CSLB classification C-33) must carry a $25,000 contractor’s license bond to maintain an active license — the same bond requirement that applies to nearly all CSLB license classifications.
What is artisan use on an auto policy?
“Artisan use” is a vehicle-use classification that covers occasional use of a personal vehicle to travel to job sites and carry tools or materials for a trade. It’s typically added as an endorsement to a personal auto policy; contractors who use a vehicle more heavily, or who have it titled to the business, usually need a full commercial auto policy instead.
How much liability insurance does an artisan contractor need in California?
There’s no single statewide minimum for general liability insurance set by the CSLB — requirements come from your license classification, contract terms, and the general contractors or clients you work with, who often set their own minimums (commonly $1 million per occurrence). Talk to your agent about the limits typical for your trade and project size.
Sources
- CSLB — License Requirement for Minor Work Increases from $500 to $1,000 (Bulletin #24-07)
- CSLB — What Kind of Contractor Do You Need? ($1,000 licensing threshold)
- CSLB — C-33 Painting and Decorating Contractor (classification)
- BLS — Painters, Construction and Maintenance (Occupational Outlook Handbook)
Akilino Jacky

