

X
Roseville
Get In Touch With Us
-

Address:
16224 E 13 Mile Rd.
Roseville, MI, 48066, United States -

Phone: 586-415-4214
-

Fax: 916-400-2625
-

Email: [email protected]
Office Hours:
-
Mon-Fri: 9:00 AM – 5:00 PM
-
Sat: Closed/By Appointment Only
-
Sun: Closed/By Appointment Only
About Roseville
Insurance in Roseville, MI
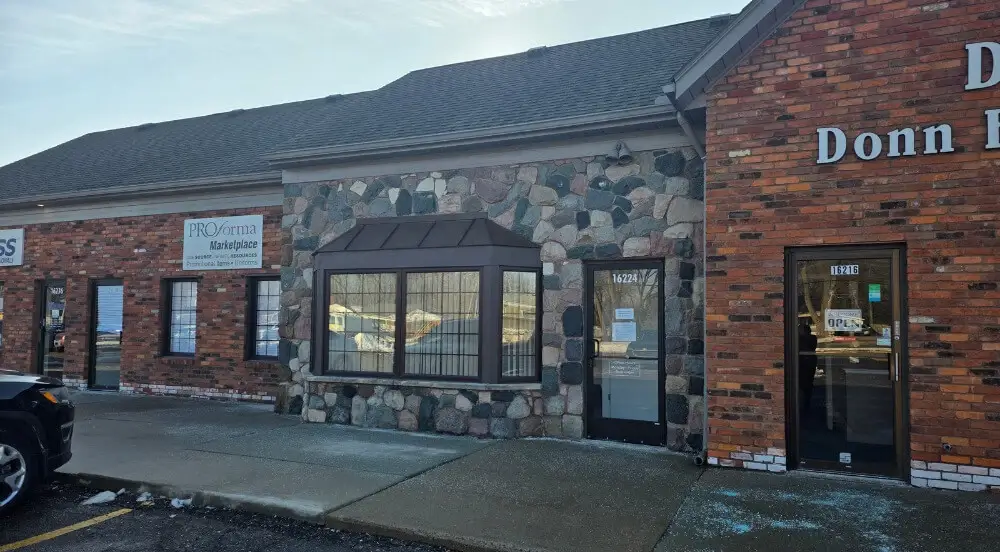
Inszone writes insurance in Roseville, MI from our office at 16224 E 13 Mile Rd. The office is on East 13 Mile Road in southern Macomb County, a short drive from St. Clair Shores and the Lake St. Clair shoreline.
This office was Brinch Insurance Agency, which has served Roseville since 2001 and joined Inszone with its team and phone number intact. Savanna Marchesani and Shannon Marchesani, QPLS, are the Personal Insurance Specialists here.
As an independent insurance agency in Roseville we represent many carriers rather than one. In Michigan that matters most on auto, where the same driver can see very different prices depending on which PIP level and liability limits a carrier is quoting — and a captive agent can only show you one carrier’s version of that.
Personal Insurance in Roseville, MI
For Roseville households we write auto, home, renters, condo and landlord policies, personal umbrella liability, and specialty lines including motorcycle, boat, RV and classic car.
Anyone comparing auto insurance in Roseville, MI is buying into a system no other state uses. Since the 2019 reform, you choose your personal injury protection medical level from six options — and if you choose nothing, the default is unlimited. The Michigan Catastrophic Claims Association assessment is attached to policies that carry unlimited PIP, which is one reason the PIP choice moves the premium as much as it does. Most drivers do not remember which level they picked, and it is the first thing worth checking on a renewal.
Two more pieces sit alongside PIP. Property protection insurance is mandatory and handles damage your vehicle does to other people’s property in Michigan, buildings, fences, properly parked cars, rather than running it through a liability limit. And Michigan’s mini tort lets you recover up to $3,000 from an at-fault driver for vehicle damage your own policy did not pay, with optional coverage available for the other side of that claim. Neither is well understood, and both show up the first time there is a collision.
Roseville car insurance quotes also depend on the residual bodily injury liability limit. The statutory minimum is $50,000 per person and $100,000 per accident, but the default if you make no selection is $250,000 and $500,000 — so a lower limit on your policy means somebody signed to choose it.
For home insurance in Roseville, MI the conversation is mostly water. Flood is excluded from the standard homeowners form, and water or sewer backup is not included automatically either — the sewer backup and sump overflow endorsement is a separate add-on, and on the older housing stock in southern Macomb it is the one most homeowners are missing. Ice dam and freeze losses are the other seasonal conversation, and it is a better one to have in October than in February.
Roseville home insurance renewals are also worth reading line by line for roof settlement terms, since a policy can quietly move from replacement cost to actual cash value on an older roof. Renters insurance is written around your contents and personal liability rather than the building, and most leases here now ask for a liability limit in writing.
Life, health and Medicare coverage in Roseville, MI, can be quoted through our wider team alongside the auto and home policies.
Business Insurance in Roseville, MI
For Roseville and Macomb County employers, our commercial team places general liability, commercial property, business owner’s policies, commercial auto and fleet, workers’ compensation, cyber liability, professional liability and surety bonds. The Roseville insurance office is a personal-lines team, so business accounts are quoted with Inszone’s commercial specialists: you can still start the conversation here.
Michigan uses a threshold for workers’ compensation rather than requiring it from the first hire. An employer needs coverage at three or more employees at one time, or at one or more employees working 35 or more hours a week for 13 weeks or longer in the preceding 52 weeks. That second test is the one that catches people out: a part-time employee whose hours creep up over a busy season can bring a one-person business inside the requirement without anyone deciding it should.
Contractors, light manufacturing and automotive suppliers, retail along Gratiot, restaurants and professional services are all lines we write regularly. Certificates of insurance and additional insured endorsements are turned around quickly, because that is usually what is holding up a job.
Inszone Insurance agency near me
Our Roseville insurance office is open Monday to Friday, 9:00am to 5:00pm. Call 586-415-4214, use the quote form on this page, or come by 16224 E 13 Mile Rd.
From 13 Mile Road we also work with clients in Eastpointe, St. Clair Shores, Warren, Fraser, Clinton Township, Sterling Heights and across Macomb County. Whether you are working out which PIP level you actually chose, checking whether sewer backup is on your homeowners policy, trying to recover a deductible through mini tort, or sorting out whether a part-time hire has triggered workers’ compensation, our insurance specialists can talk through the options available for your situation.
FAQs
What are the minimum auto insurance requirements in Michigan?
Michigan is unlike anywhere else. The residual bodily injury liability minimum is $50,000 per person and $100,000 per accident, but if you make no selection the default is $250,000 / $500,000. In-state property damage runs through mandatory property protection insurance rather than the liability limit. And since the 2019 reform you choose your PIP medical level from six options, with unlimited as the default if you choose nothing.
What happens if I did not choose a PIP level in Michigan?
You have unlimited PIP medical coverage, because that is the default the 2019 reform set for anyone who does not make a selection. The lower options exist mainly for drivers with qualifying health coverage or Medicare, and each comes with conditions about what other coverage has to be in place. Unlimited PIP is also the level that carries the Michigan Catastrophic Claims Association assessment. Which level makes sense depends on your health coverage and your household, so it is worth reviewing with a specialist rather than choosing on premium alone.
What is Michigan’s mini tort?
It is the right to recover up to $3,000 from an at-fault driver for damage to your vehicle that your own policy did not pay — most often your collision deductible, or the repair itself if you do not carry collision. Because Michigan’s no-fault system otherwise limits suits between drivers, mini tort is the main route for that money. Optional coverage exists on the other side, for when you are the driver at fault and the claim is made against you.
Is water backup covered by my Michigan homeowners policy?
Not automatically. The state’s own regulator points out that flood is not covered and water or sewer backup is not automatically covered either — the sewer backup and sump overflow endorsement is a separate add-on, and it is the single most useful thing most Michigan homeowners are missing. Ice dam and freeze losses are the other seasonal conversation worth having before winter rather than during it.
Does my Roseville business need workers’ compensation insurance?
Michigan uses a threshold: three or more employees at one time, or one or more employees working 35 or more hours a week for 13 weeks or longer in the preceding 52 weeks. Agricultural and domestic employment have their own hour-and-week tests.
Is this the same office that was Brinch Insurance Agency?
Yes. Brinch Insurance Agency has served Roseville since 2001 and continues from 16224 E 13 Mile Rd as part of Inszone Insurance, with the same team and the same phone number. Policies carried over.
How do I get a quote from your Roseville insurance office?
Call 586-415-4214 or use the quote form on this page, and come by 16224 E 13 Mile Rd if you would rather do it in person. Have your current declarations page to hand if you can — for auto, that is where your PIP level and liability limits are shown — and for commercial coverage your revenue, payroll by class and recent loss runs. If a carrier has sent you a non-renewal or cancellation notice, bring it; the date on it changes what options are open.
Our Roseville Team
-


How To Get There