A personal articles floater is a type of insurance that protects specific high-value belongings — jewelry, art, collectibles, and similar items — from theft, loss, or damage that your standard homeowners or renters insurance might not fully cover. Certain possessions hold more than just monetary worth, carrying personal, emotional, and historical value worth protecting properly.
Certain possessions hold more than just monetary worth, they carry personal, emotional, and historical value. A personal articles floater helps protect these valuables from theft, loss, or damage that your standard homeowners or renters insurance might not fully cover.
Whether you own fine jewelry, art, collectibles, or rare electronics, this specialized coverage ensures you can recover their true value if the unexpected occurs.
Key Points
- A personal articles floater is a personal inland marine policy that insures specific high-value items — jewelry, art, cameras, collectibles — beyond what a standard homeowners policy covers (IRMI, NAIC).
- Standard homeowners policies typically cap coverage for jewelry or fine art at a few thousand dollars combined; a floater insures each item individually at its full appraised value.
- Floaters are usually written on an open-peril basis, covering accidental loss and mysterious disappearance in addition to theft and damage.
- Scheduled floaters cover items individually at appraised value; blanket floaters set one combined limit per category without requiring appraisals.
- AARP doesn’t underwrite insurance directly — AARP-branded homeowners coverage comes through a partner carrier, and a personal articles floater works the same way as with any other homeowners policy.
What Is a Personal Articles Floater Insurance Policy?
A personal articles floater insurance policy is designed to cover valuable, movable property that falls outside the limits or exclusions of your homeowners or renters policy.
Most standard homeowners insurance policies include sublimits for certain high-value items, often only a few thousand dollars for jewelry, art, or collectibles. A personal articles floater bridges this gap, offering broader protection and higher limits for your most valuable belongings.
Unlike basic coverage, a personal floater insurance policy typically provides “open peril” protection, meaning your items are covered against all risks except those specifically excluded. That includes loss, theft, mysterious disappearance, or accidental breakage, perils standard homeowners insurance often excludes.
Common exclusions in personal articles floater insurance include wear and tear, gradual deterioration, war, and intentional damage.
Does Homeowners Insurance Cover Jewelry or Valuables?
Your homeowners insurance does cover jewelry, fine art, and valuables, but only up to a certain amount, and usually with significant restrictions. Standard policies set sublimits for categories like jewelry, firearms, or silverware, typically capping coverage at $1,500–$2,500 per item or category.
That means a $10,000 engagement ring or $25,000 art piece wouldn’t be fully insured under a basic homeowners policy. The solution is a personal property floater or personal articles floater policy, which provides dedicated coverage based on each item’s appraised value.
These floaters also allow you to customize deductibles, select replacement or repair terms, and protect items anywhere in the world, not just at your residence.
Read more: homeowners insurance limits for jewelry
How Does a Personal Articles Floater Work?
A personal articles floater policy functions as an add-on or standalone policy that supplements your existing homeowners or renters insurance. It offers flexible limits, low deductibles, and itemized protection for valuable personal property.
Here’s how it generally works:
- Coverage type: “Open peril” coverage protects your listed items unless specifically excluded.
- Coverage amount: Based on appraised or agreed-upon value, ensuring full reimbursement for losses.
- Deductible: Typically lower (or even $0) than standard homeowners insurance.
- Eligibility: Any high-value movable property, such as jewelry, cameras, instruments, collectibles, or antiques, can qualify.
The personal articles floater exclusions vary by insurer but may include wear, corrosion, insects, or manufacturing defects. However, the key advantage is its broad protection for perils often left out of other policies, such as accidental loss or mysterious disappearance.
For instance, if you drop a diamond earring down the drain or lose a camera while traveling, your homeowners insurance likely won’t respond, but your personal articles floater insurance would.
What Items Can Be Covered by Personal Article Insurance?
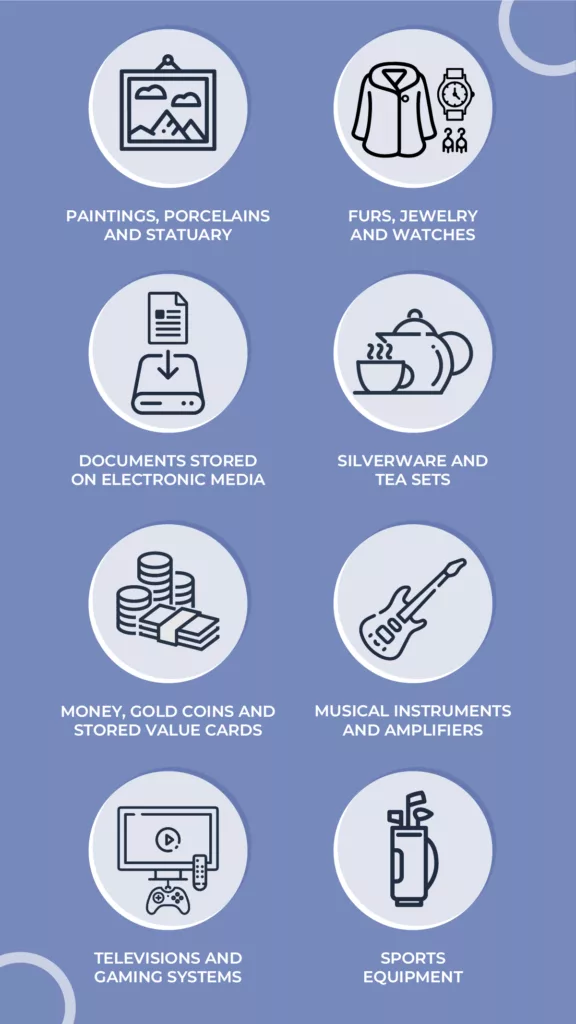
A personal article floater policy can insure nearly any valuable movable item, provided it’s itemized, appraised, and documented. Typical categories include:
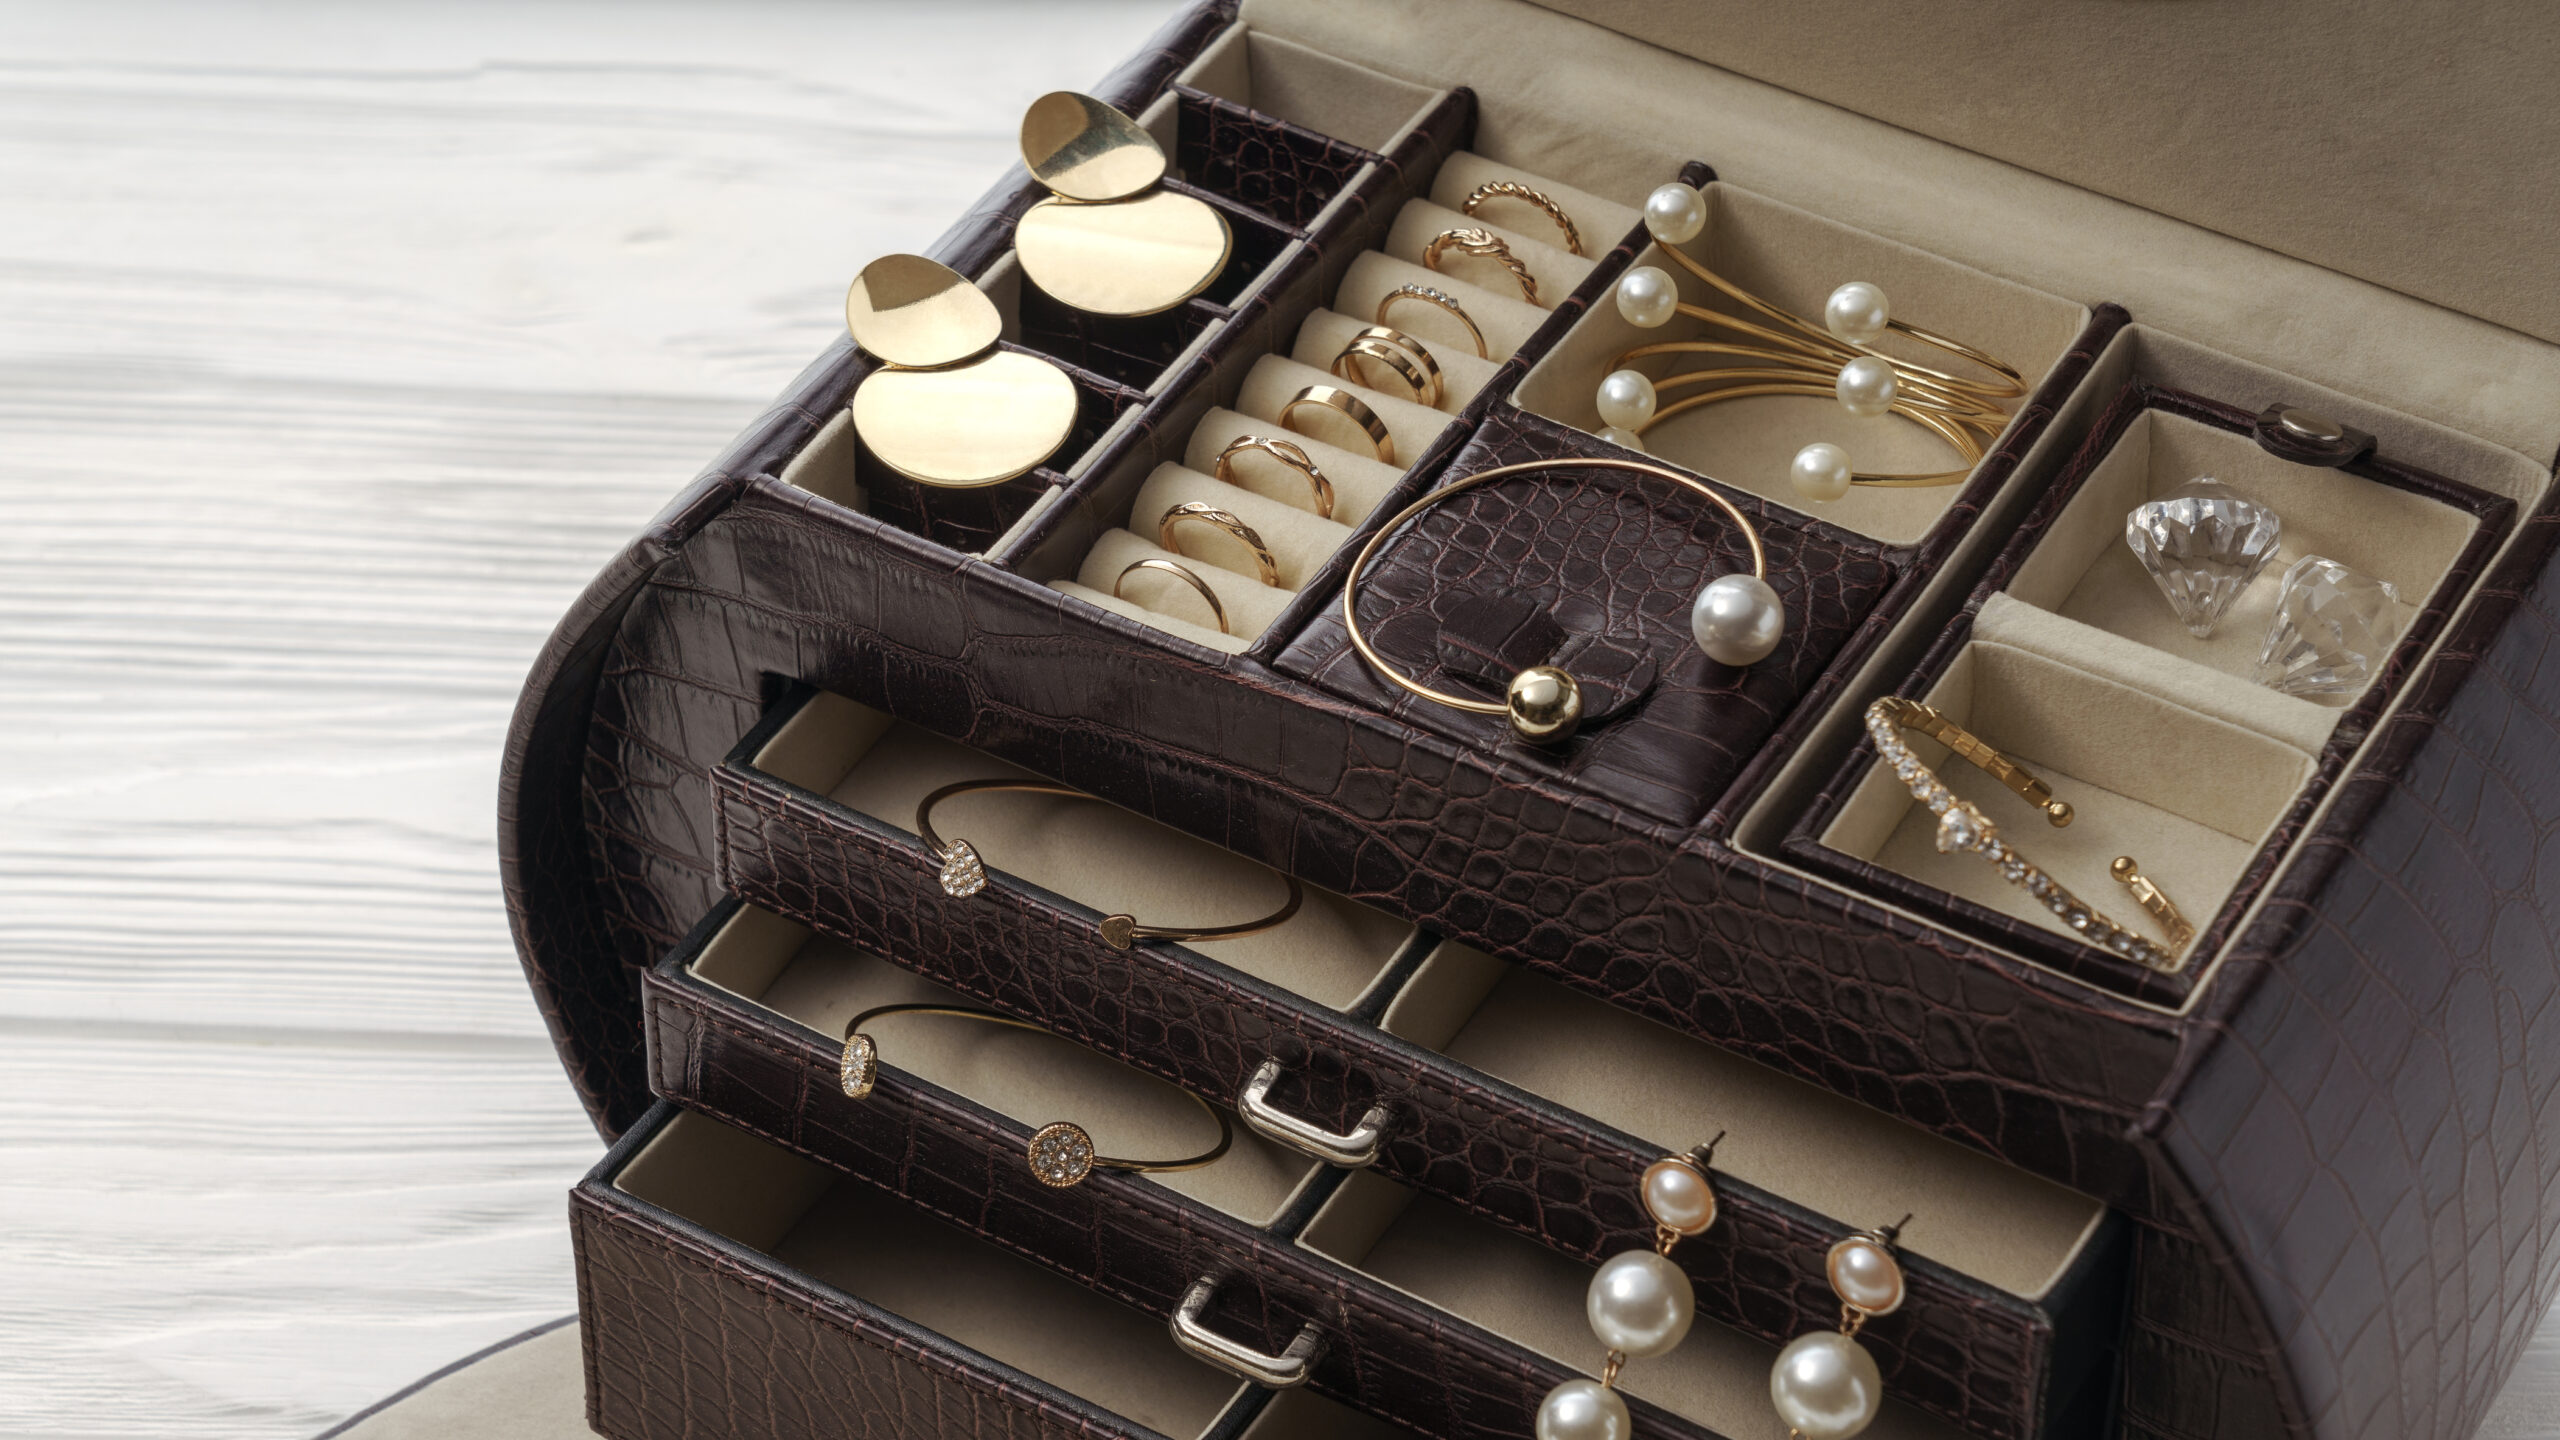
Jewelry and Luxury Accessories
Rings, watches, necklaces, and handbags that are easy to lose or steal and often appreciate over time.
Fine Art and Antiques
Paintings, sculptures, and collectibles with high financial or cultural value that may be fragile or irreplaceable.
Electronics and Cameras
Laptops, high-end cameras, and audio gear prone to theft or accidental damage.
Collectibles and Memorabilia
Rare coins, stamps, sports memorabilia, or trading cards with unique sentimental and market value.
Learn: The ultimate guide to protecting your expensive gifts
How to Obtain a Personal Articles Floater
Securing floater insurance is straightforward and typically involves:
- Contacting your insurer or agent: Ask whether your carrier offers personal article floaters as endorsements or separate policies.
- Providing documentation: Supply receipts, appraisals, or certificates of authenticity to verify ownership and value.
- Getting an appraisal: Most insurers require professional appraisals for items like jewelry, art, and antiques.
- Reviewing terms: Understand your coverage limits, deductible, exclusions, and claim process before binding the policy.
Some insurers require you to have an existing homeowners or renters policy with them to qualify for a personal articles floater policy, while others allow stand-alone options for specific high-value items.
Comparing Providers and Coverage Options
When evaluating insurers, look at three main factors:
- Coverage flexibility: Ensure your policy covers accidental loss, theft, and mysterious disappearance worldwide.
- Customer service and claims: Research responsiveness and fairness in claim settlements.
- Cost and deductibles: While personal floater insurance tends to cost more per item than standard coverage, its broader protection and low deductibles make it worthwhile.
Comparing multiple insurers ensures you find the right balance between cost and protection for your valuables.
Why Personal Article Insurance Matters for Your Valuables
From heirloom jewelry to professional equipment, your most valuable possessions deserve coverage that reflects their worth. A personal articles floater offers peace of mind by providing protection far beyond what homeowners insurance can deliver.
With customizable coverage, low deductibles, and worldwide protection, a personal article floater policy ensures that your prized possessions, both sentimental and financial, are secure, no matter where life takes you.
Frequently Asked Questions About Personal Articles Floater Insurance
What is a personal articles floater and what does it cover?
A personal articles floater is a policy — usually classified as personal inland marine coverage — that insures specific high-value, movable items like jewelry, fine art, cameras, and collectibles beyond the sublimits of a standard homeowners or renters policy. It typically covers loss, theft, and accidental damage on an open-peril basis, wherever the item is located.
What is the difference between a floater and standard homeowners insurance?
Standard homeowners insurance caps coverage for categories like jewelry or fine art at a few thousand dollars combined, regardless of what any single item is worth. A personal articles floater insures each item individually at its appraised value, with broader open-peril coverage and often a lower or $0 deductible.
What items can be covered under a personal articles floater?
Nearly any valuable, movable, and documentable item can qualify, including jewelry and watches, fine art and antiques, cameras and electronics, musical instruments, furs, and collections of coins, stamps, or memorabilia.
How do I file a claim on a personal articles floater?
Contact your agent or carrier as soon as possible after a loss, and provide your original appraisal or purchase documentation along with a police report (for theft) or photos of the damage. Because floaters are typically written on an appraised or agreed value basis, claims are often settled with less back-and-forth over item value than a standard homeowners claim.
Does AARP offer personal articles floater insurance?
AARP itself doesn’t underwrite insurance policies — it’s a membership organization that partners with insurance carriers to offer AARP-branded homeowners and auto coverage to members. If your AARP-branded homeowners policy offers a personal articles floater option, it works the same way as with any other homeowners carrier: as an endorsement or a standalone policy for your high-value items.
How much does a personal articles floater cost?
Cost depends primarily on the type and value of the item, its location, and the deductible you choose — jewelry and fine art typically cost more to insure per dollar of value than electronics, for example. Ask your agent for a quote based on your specific items and appraisals rather than a general estimate.
What is the difference between a scheduled and blanket personal articles policy?
A scheduled policy lists each item individually with its own appraised value, giving you full coverage for that specific item with no per-item cap. A blanket policy sets one combined limit for an entire category, such as all jewelry, which skips the appraisal requirement but usually caps the payout per item — a better fit for several moderate-value items than one or two very expensive ones.
Juan Cruz

