What are the most common restaurant insurance claims?
- Slip, trip & fall (customers and staff) — Wet floors, cluttered aisles, uneven surfaces, and poor lighting continue to drive general liability and workers’ compensation claims.
- Cuts & burns (back of house) — Knives, slicers, fryers, and hot surfaces are frequent injury sources without consistent PPE and safe-use SOPs.
- Kitchen fires & smoke damage — Grease build-up and unserviced hood/duct systems remain leading ignition factors; losses escalate quickly to BI/EE (business income/extra expense).
- Foodborne illness & contamination — Norovirus, Salmonella, and E. coli exposures rise when ready-to-eat foods contact bare hands or when time/temperature controls slip.
- Equipment breakdown & spoilage — Refrigeration failures, voltage spikes, and utility outages cause food spoilage and downtime.
- Cyber & payment card breaches — POS intrusion, phishing, and misconfigurations target restaurants because of high card volume and lean IT controls.
- Alcohol service & assault/battery — Overservice and altercations create third-party injury claims under state dram shop/social host laws.
- Delivery & Hired/Non-Owned Auto (HNOA) — Employee vehicles used for errands/delivery generate auto liability even if the business owns no cars.
- Property damage from weather/water — Wind, water, sewer backup, and power loss damage interiors and contents; coverage often depends on endorsements.
- Employment practices (EPLI), wage & hour — Tip pooling, overtime, and retaliation allegations continue across the sector.
- ADA/accessibility (including websites) — Title III accessibility lawsuits (site, app, and physical access) remain active in consumer-facing industries.
Where and when do these claims happen?
- Front-of-house: Entrances, restrooms, and crowded aisles → slip/falls.
- Back-of-house: Fryers/grills, knife stations, and dish areas → burns/cuts and fires.
- Bar areas/late hours: Overservice, assault & battery, and liquor liability.
- Cold storage overnight: Outages and compressor failures → spoilage/BI.
- POS and Wi-Fi networks: Phishing, credential stuffing, POS malware → breach costs, PCI assessments, and downtime.
- Curbside/delivery: Parking lot fender-benders and employee car use → HNOA claims.
Why do these trends matter for your insurance costs?
The commercial P&C market in 2025 is moderating, but property, auto, and umbrella remain firm relative to pre-2020 norms. Casualty severity is influenced by litigation trends (“nuclear verdicts”), which push up umbrella pricing and attachment points. Strong prevention and documented controls can help your broker negotiate better terms, especially where carriers scrutinize cooking fire protection, liquor controls, cyber hygiene, and delivery protocols.
Who is most affected—by operation type?
- Full-service restaurants: More slip/fall and liquor exposure; steady worker injury rates.
- Quick-service/delivery-heavy: Higher HNOA auto and cyber exposure (card volume + app/online orders).
- Bars & taverns: Liquor liability and assault/battery; in some states, mandated higher limits or tightened underwriting.
- Caterers/food trucks: Mobile auto risks, generator/equipment breakdown, and off-premises slip/fall.
How to prevent losses and match coverages
| Claim Type | Key Triggers | Prevention Essentials | Typical Coverage Response |
|---|---|---|---|
| Slip/Trip/Fall (Customer) | Wet floors, clutter, dim lighting |
|
General Liability; Umbrella (severity) |
| Cuts & Burns (Staff) | Knives, slicers, fryers |
|
Workers’ Compensation |
| Kitchen Fire | Grease build-up; unserviced hoods/ducts |
|
Property (incl. BI/EE); Umbrella |
| Foodborne Illness | Bare-hand RTE handling; temp abuse |
|
GL (Products/Completed Ops); Food Contamination/Spoilage; BI (endorsement) |
| Equipment Breakdown & Spoilage | Compressor failure; power surge/outage |
|
Equipment Breakdown; Spoilage; Utility Service – Direct Damage/Time Element |
| Cyber/Data Breach | Phishing; POS intrusion; misconfig |
|
Cyber Liability (IR firm, PCI assessments, BI & extortion as purchased) |
| Liquor Liability / A&B | Overservice; inadequate controls |
|
Liquor Liability; Assault & Battery endorsement; Umbrella |
| Delivery / HNOA | Employee vehicles; gig-driver relationships |
|
Hired & Non-Owned Auto; Umbrella |
| Property/Weather & Water | Wind/water; sewer backup; outage |
|
Property; Flood (separate); Utility Service; BI/EE |
| EPLI / Wage & Hour | Tips/overtime; retaliation |
|
EPLI (defense/settlement; wage & hour sublimits vary) |
| ADA / Accessibility (incl. Web) | Physical barriers; WCAG gaps |
|
GL may defend; risk reduced via compliance work |
Quick prevention checklists
Slip/Trip/Fall — Daily FOH Walk
- Swap saturated mats at entries; place wet-floor cones until dry.
- Keep aisles clear; replace burnt bulbs; log incidents with photos within 24 hours.
Kitchen Fire — Weekly/Monthly
- Inspect hood & duct per NFPA 96 frequency; verify suppression tags.
- Seat grease filters properly; keep combustibles away from open flame.
Food Safety — Every Shift
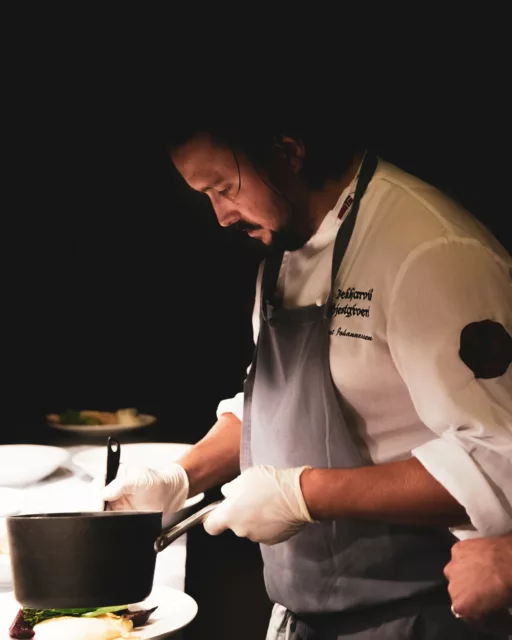
- No bare-hand contact with ready-to-eat foods; strict handwashing timing.
- Log cold-hold/hot-hold temps; label/date; exclude ill workers.
Cyber — Monthly
- Enforce MFA; segment POS from guest Wi-Fi; run phishing simulations.
Liquor Controls — Nightly
- Check IDs with scanners; document refusals; maintain incident/ejection logs.
FAQs & misconceptions
We don’t own delivery vehicles, so we don’t need auto coverage
False. Employee vehicles used for any business purpose create HNOA exposure. Consider HNOA and umbrella limits.Property policies automatically cover spoilage and power outages
Not always. Spoilage and off-premises power are commonly separate endorsements with sublimits and waiting periods.ADA only means ramps and bathrooms
Website and app accessibility claims are common. Aim for WCAG 2.2 AA and keep an audit trail of fixes.Workers’ comp is flat, so safety can wait
Claims still affect your experience mod and total cost of risk. Keep training, SOPs, and documentation tight.Sources and Further Reading
- NFPA — Restaurant/Kitchen Fire Data | NFPA 96 Overview
- FDA — Food Code (2022 edition)
- CDC — Foodborne Illness Estimates | CDC — Norovirus in Food Settings
- BLS — Injury & Illness Data (Full-Service Restaurants)
- Verizon — Data Breach Investigations Report (2025)
- NCSL — Dram Shop & Social Host Liability by State
- CIAB — Quarterly P/C Market Survey
- Seyfarth — ADA Title III Litigation Year-in-Review
- U.S. DOL — Wage & Hour Division (Restaurant Enforcement)
- Insurance Journal — Litigation Trends
- Swiss Re Institute — Nuclear Verdicts & Liability Trends
Jared Strong
Follow Us:

